
How to Prepare Your Home for Appraisal When SellingPreparing for a home appraisal is less about decoration and more about access, condition, and clear information. The appraiser needs to
Dated: August 19 2026
Views: 80
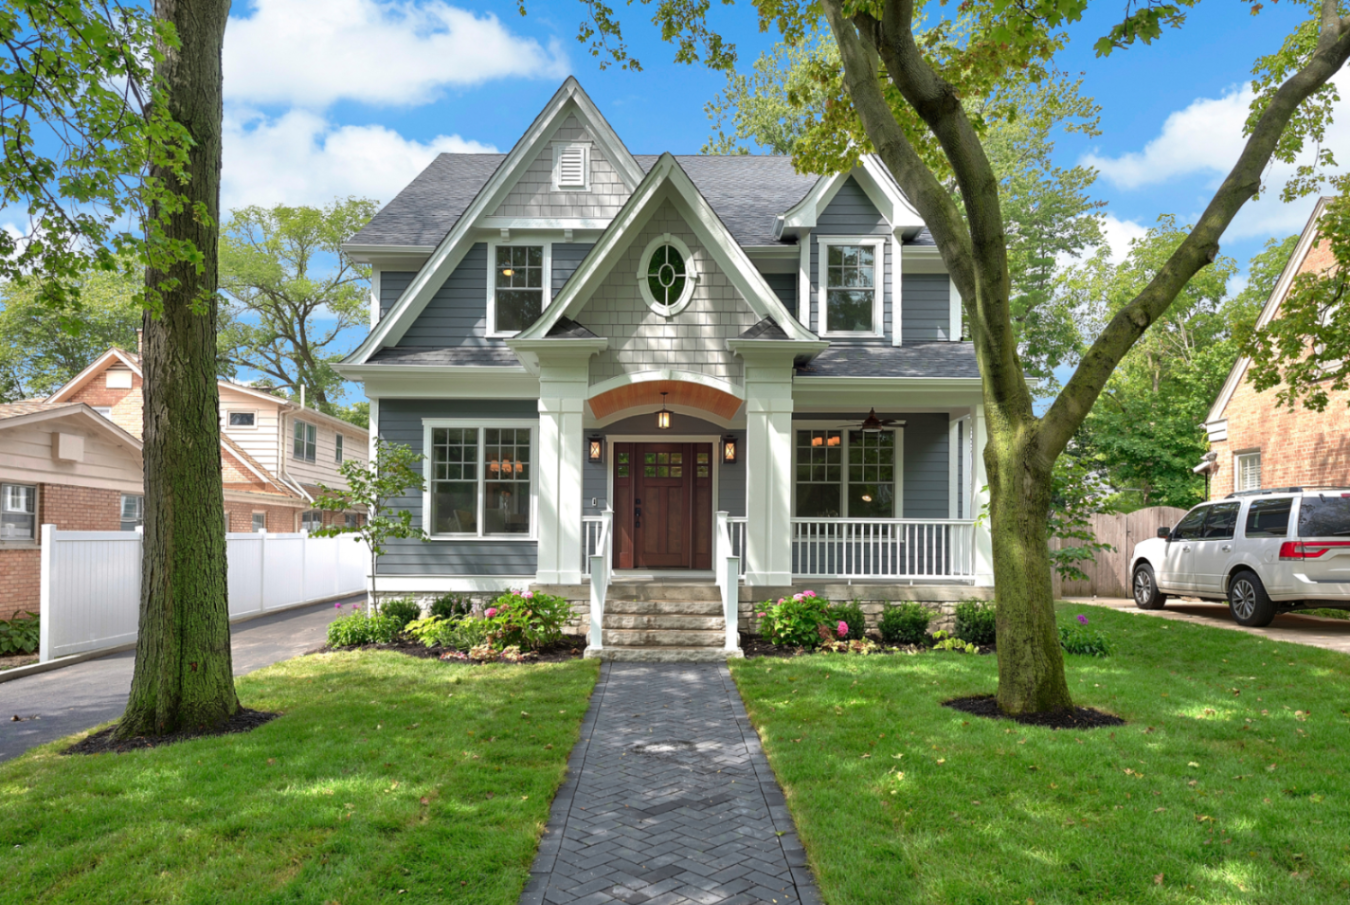
Preparing for a home appraisal is less about decoration and more about access, condition, and clear information. The appraiser needs to inspect the property, confirm its features, and compare it with relevant sales. Sellers can help by fixing visible maintenance issues, making every area easy to reach, and providing a concise record of permitted improvements. The goal is not to pressure the appraiser. It is to make sure the property can be evaluated accurately.
A home appraisal is a professional opinion of a property’s market value, prepared by a qualified appraiser. In a financed purchase, the lender usually orders the appraisal to assess the property that will secure the mortgage. The appraiser reviews the home, the site, public records, and recent comparable sales, then produces a written report. An appraisal is not the same as a home inspection. An inspector focuses on the physical condition of the home and identifies defects for the buyer. An appraiser considers condition as part of a broader value analysis. The appraiser is not there to provide a complete technical review of every system.
A home appraisal costs several hundred dollars, but there is no single national fee. Larger homes, rural properties, unique designs, complex sites, rush requests, and specialized loan requirements may incur higher costs. In a typical financed sale, the buyer pays the fee through the lender. The amount should appear in the buyer’s loan disclosures.
Sellers do not usually choose the lender’s appraiser. Some sellers order a separate pre-listing appraisal, but that report may not replace the appraisal required by the buyer’s lender.
Appraisers look for recent sales that are similar in location, size, condition, age, design, and site. No comparison is perfect, so the appraiser makes adjustments based on market evidence. A high asking price or a neighbor’s unsold listing does not prove value.
Neighborhood demand, lot size, views, access, school boundaries, traffic, noise, flood risk, and nearby land uses may affect value. Some features are positive for one buyer and less important to another, so the appraiser looks at how the market has responded.
Gross living area, bedroom and bathroom count, functional layout, and permitted additions can matter. Finished space may be treated differently depending on whether it is above-grade, below-grade, legally permitted, heated, or accessible from the main home. Public records and the actual property should be reasonably consistent.
The roof, foundation, exterior, windows, heating and cooling, plumbing, electrical systems, kitchens, bathrooms, and interior finishes can influence the condition rating. Appraisers distinguish normal wear from deferred maintenance or damage.
A new roof or updated kitchen may help, but the appraiser does not simply add the renovation cost to the value. The question is how buyers in that market respond to the improvement. Work completed without required permits may create questions rather than value.
Fix items that suggest neglect or prevent normal use. Examples include leaking faucets, broken locks, damaged steps, loose railings, cracked windows, missing outlet covers, burned-out lights, peeling exterior paint, or doors that do not close. Major repairs should be discussed with the listing agent before money is spent.
The appraiser may need to view the bedrooms, bathrooms, the garage, attic access, the basement, the crawl space, mechanical rooms, utility panels, outbuildings, and the full exterior. Open gates and doors, secure pets, turn on utilities, and clear stored items away from important systems.
List meaningful improvements with completion dates, permits, and contractor information when available. Keep the document factual. A clear note such as ‘roof replaced in 2023 with permit’ is more useful than a long sales description. Include additions, major system replacements, and energy or accessibility upgrades that may not be obvious during the visit.
Review the listing information for obvious errors in bedroom count, bathroom count, lot size, or finished area. If there is a discrepancy between public records and the home, gather permits, plans, surveys, or other documents that may explain it. Do not present unverified square footage as fact.
The listing agent can provide a short package of recent comparable sales, pending sales, competing listings, and factual notes about differences. The appraiser makes an independent decision, but accurate market information can help when a property is unusual or when public records are incomplete.
Every day, clutter does not directly determine value. Heavy clutter can block inspection or make the condition harder to judge. Basic cleaning, trimmed walkways, working lights, and clear access help the visit proceed smoothly. Expensive staging is not required for the appraisal itself.
The appraiser may measure the exterior, photograph rooms and site features, note materials and condition, and ask factual questions. Sellers should answer directly and avoid following the appraiser through every room. The agent may attend where local practice allows. No one should attempt to influence the result or suggest that the transaction depends on a particular number.
A low appraisal does not automatically end the sale. Start by reviewing the report for factual errors, such as an incorrect room count, a missed permitted addition, a wrong lot size, or an unsuitable comparable sale. The buyer can ask the lender about its value reconsideration process. A strong request identifies specific errors or provides better comparable sales. It should not simply argue that the contract price is higher.
The parties may also renegotiate the price, adjust credits, extend the timeline, or have the buyer cover part of the difference. The available options depend on the contract, financing, appraisal contingency, and lender rules. A second appraisal is not guaranteed and is generally at the lender’s discretion.
Normal clutter does not usually change market value. It can become a problem if the appraiser cannot access rooms or systems, or if the appraiser cannot see damage or deferred maintenance.
Yes, if the list is brief, accurate, and supported by dates or permits. Focus on major work and features that may not be visible.
The seller usually works through the buyer and the buyer’s lender. The lender may reconsider the value when the request points to factual errors or stronger market evidence.
The best way to prepare for a home appraisal is to repair obvious defects, make every area accessible, confirm the listing details, and provide a clean record of improvements. A local REMAX Real Estate Group agent can help organize relevant comparable sales, identify issues before the visit, and explain the options if the appraised value does not support the contract price.
#homeappraisal #homeseller #homebuyer #firsttimehomebuyer #findmydreamhome #REMAX #REMAXRealEstateGroup #REMAXErie
How to Prepare Your Home for Appraisal When SellingPreparing for a home appraisal is less about decoration and more about access, condition, and clear information. The appraiser needs to
Back-to-School Home Setup: 4 Functional Family ZonesGetting a home ready for the school year works best around four functional zones: a dedicated work zone for kids, smart storage that keeps daily
How to Sell an Inherited HouseTo sell an inherited house, the estate or heirs must first have legal authority to transfer the property. That may happen through probate, a trust, joint ownership, or
Understanding Closing Costs: What’s Included?New home buyers are sometimes taken by surprise by closing costs, but they can range from 2% to 5% of the home’s purchase price, so
 Greater Erie Board of Realtors® Inc. All information deemed reliable but not guaranteed. All properties are subject to prior sale, change or withdrawal. Neither listing broker(s) or information provider(s) shall be responsible for any typographical errors, misinformation, misprints and shall be held totally harmless. Listing(s) information is provided for consumer's personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be
interested in purchasing. The data relating to real estate for sale on this website comes in part from the Internet Data Exchange program of the Multiple Listing Service. Real estate listings held by brokerage firms other than REMAX Real Estate Group may be marked with the Internet Data Exchange logo and detailed information about those properties will include the name of the listing broker(s) when required by the MLS. Copyright ©2026 All rights reserved.
Last Updated: September 24, 2026 5:13 PM UTC
Show More...
